 Charlie
Mastercard may be preparing for a future where it makes money not just from PAYMENTS...
but from powering the entire AGENTIC COMMERCE ecosystem.
Yesterday, Mastercard announced Agent Connect and expanded its capabilities for AI-powered shopping.
At first glance, this looks like another way to make online commerce easier.
I think something much bigger may be happening.
For decades, Mastercard’s economics have largely depended on one thing:
MORE COMMERCE → MORE CARD TRANSACTIONS → MORE NETWORK REVENUE
Agentic commerce could certainly accelerate that.
If AI agents shop, compare and transact on our behalf, Mastercard could process far more transactions.
But that alone is not reinvention.
The more interesting possibility is that Mastercard is building an entirely NEW layer of monetisation.
Because AI agents cannot simply roam around the internet buying things autonomously.
The ecosystem needs infrastructure for:
- IDENTITY
- PERMISSION
- AUTHENTICATION
- TRUST
- FRAUD PREVENTION
- TOKENISATION
- MERCHANT ACCESS
- TRANSACTION EXECUTION
And somebody has to provide it.
That may be what Mastercard is positioning itself to become.
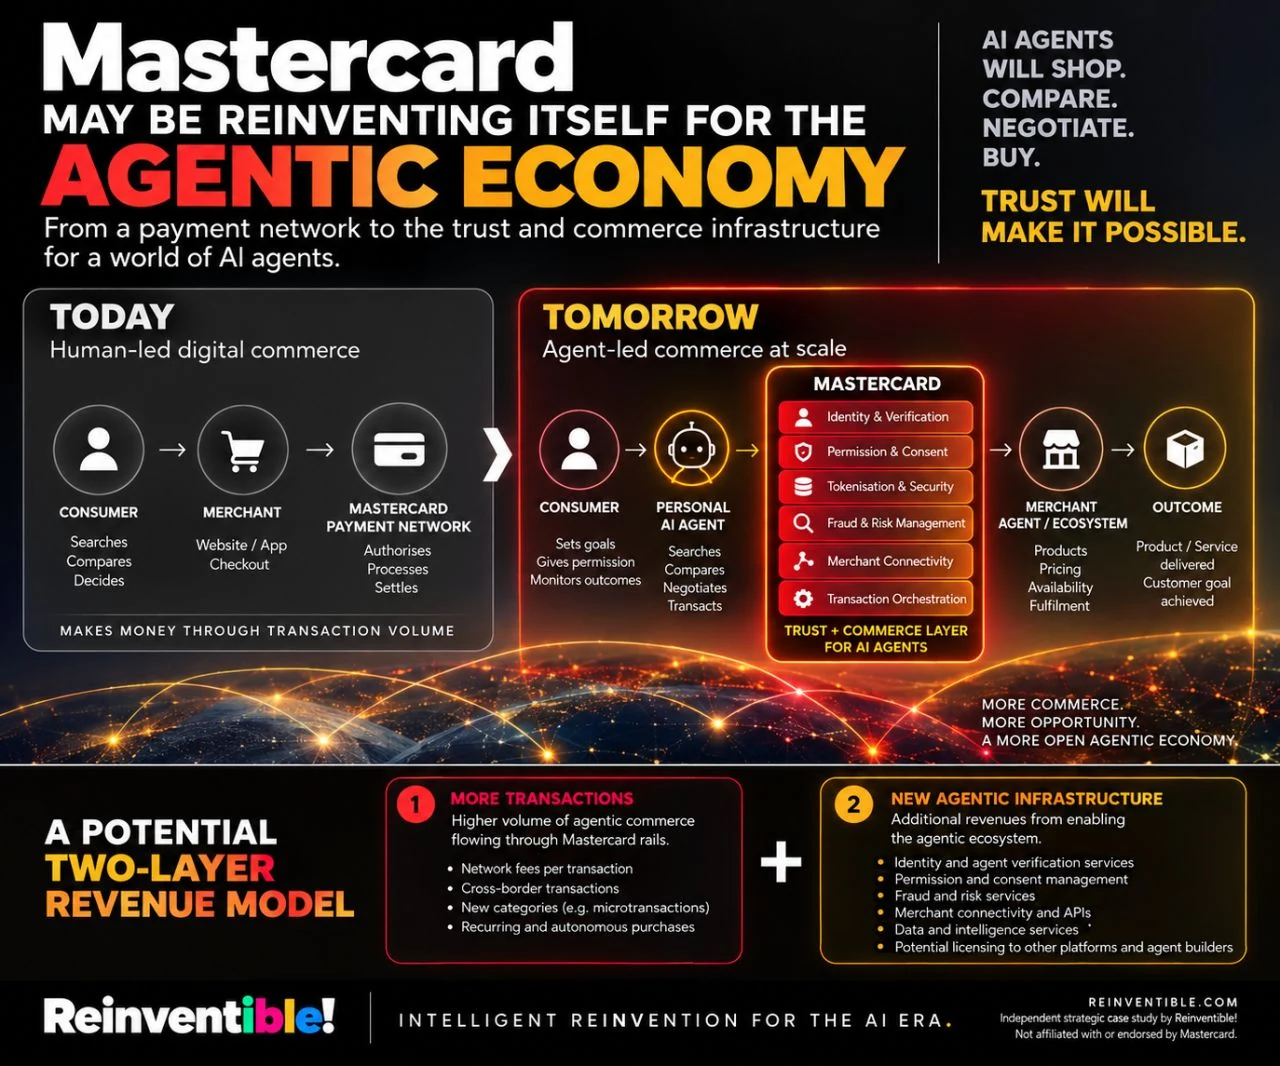
Today
CONSUMER → MERCHANT → MASTERCARD PAYMENT NETWORK → TRANSACTION
Tomorrow
CONSUMER → PERSONAL AI AGENT → MASTERCARD (TRUST + IDENTITY + PERMISSION + COMMERCE LAYER) → MERCHANT AGENT / COMMERCE ECOSYSTEM → OUTCOME
Making money twice
If this thesis is right, Mastercard could potentially make money twice.
- FIRST: More agentic transactions flowing through Mastercard rails.
- SECOND: New revenues from the infrastructure that enables agents to transact safely in the first place.
That could include services around:
- Agent verification
- Identity and authentication
- Consent and permissions
- Fraud and risk
- Tokenisation
- Merchant connectivity
- Transaction orchestration
In other words, Mastercard may be trying to move UP the value stack.
PAYMENT NETWORK → DIGITAL COMMERCE NETWORK → AGENTIC COMMERCE INFRASTRUCTURE
The strategic objective may not be to build the best shopping agent.
It may be to become the infrastructure that EVERY shopping agent needs.
That is a much more powerful position.
And it creates a potential new business model:
TRANSACTION FEES + AGENTIC INFRASTRUCTURE REVENUE
Still a hypothesis
This is still my hypothesis.
Mastercard has not publicly disclosed a separate monetisation model for all of these agentic capabilities.
But that is precisely what makes the strategic direction interesting.
The most important reinventions are usually visible in the architecture long before they are visible in the revenue line.
The company that for decades monetised the movement of money may next monetise the TRUST required for autonomous machines to move money.
That would be real reinvention.
Don’t just add AI. Reinvent for the AI era.
Originally published as a post by Charlie Ang on LinkedIn, part of his "Reinventing X for the AI Era" series. Source: Mastercard press release on Agent Connect. This is an independent strategic analysis, not affiliated with or endorsed by Mastercard.

Charlie Ang is an Intelligent Reinvention Strategist, corporate futurist and AI keynote speaker based in Singapore and speaking worldwide. He helps organisations and leaders reinvent, rewire and retool for the Age of Intelligence, and has been featured by the BBC, Financial Times, National Geographic and CNA.